Zero-Shot Time-Series Forecasting: What It Means and When It Works
 Timestral Team
Zero-shot forecasting skips training and predicts a new series from its history. Learn when that is enough, when it fails, and how to set up a fair zero-shot baseline with Timestral.
Zero-shot forecasting means using a pretrained model on a series it has never seen, without updating its weights. It is the fastest way to get a forecast from a new dataset: paste the history, choose a horizon, and read the output.
It is also easy to misuse. A zero-shot model is a strong baseline, not a substitute for understanding your data. This guide explains what it can and cannot do, and how to use it without fooling yourself.
CSV forecast studio
Paste a series, get a probabilistic forecast.
One value per row, or a date column plus one or more numeric columns. Timestral returns a median forecast and a likely range. The demo runs on the public Hugging Face Space; the API is the paid product.
How zero-shot forecasting works
A foundation model is trained on a large corpus of time series. It learns patterns that transfer across domains: trend, seasonality, level shifts, volatility clustering, missing-data behavior. At inference time, you provide a history and a horizon; the model conditions on the history and produces a forecast.
No gradient updates, no hyperparameter search, no training set. That is the whole appeal.
What it is good at
- Fast baselines. You can forecast a new series in minutes, not weeks.
- Many series. Score hundreds of SKUs, sensors or regions with the same model.
- Probabilistic output. Timestral returns 21 quantiles, so you get uncertainty without building a separate model.
- Cold start. A new product or a new region with a short history can still get a forecast.
Where it fails
1. Structural breaks
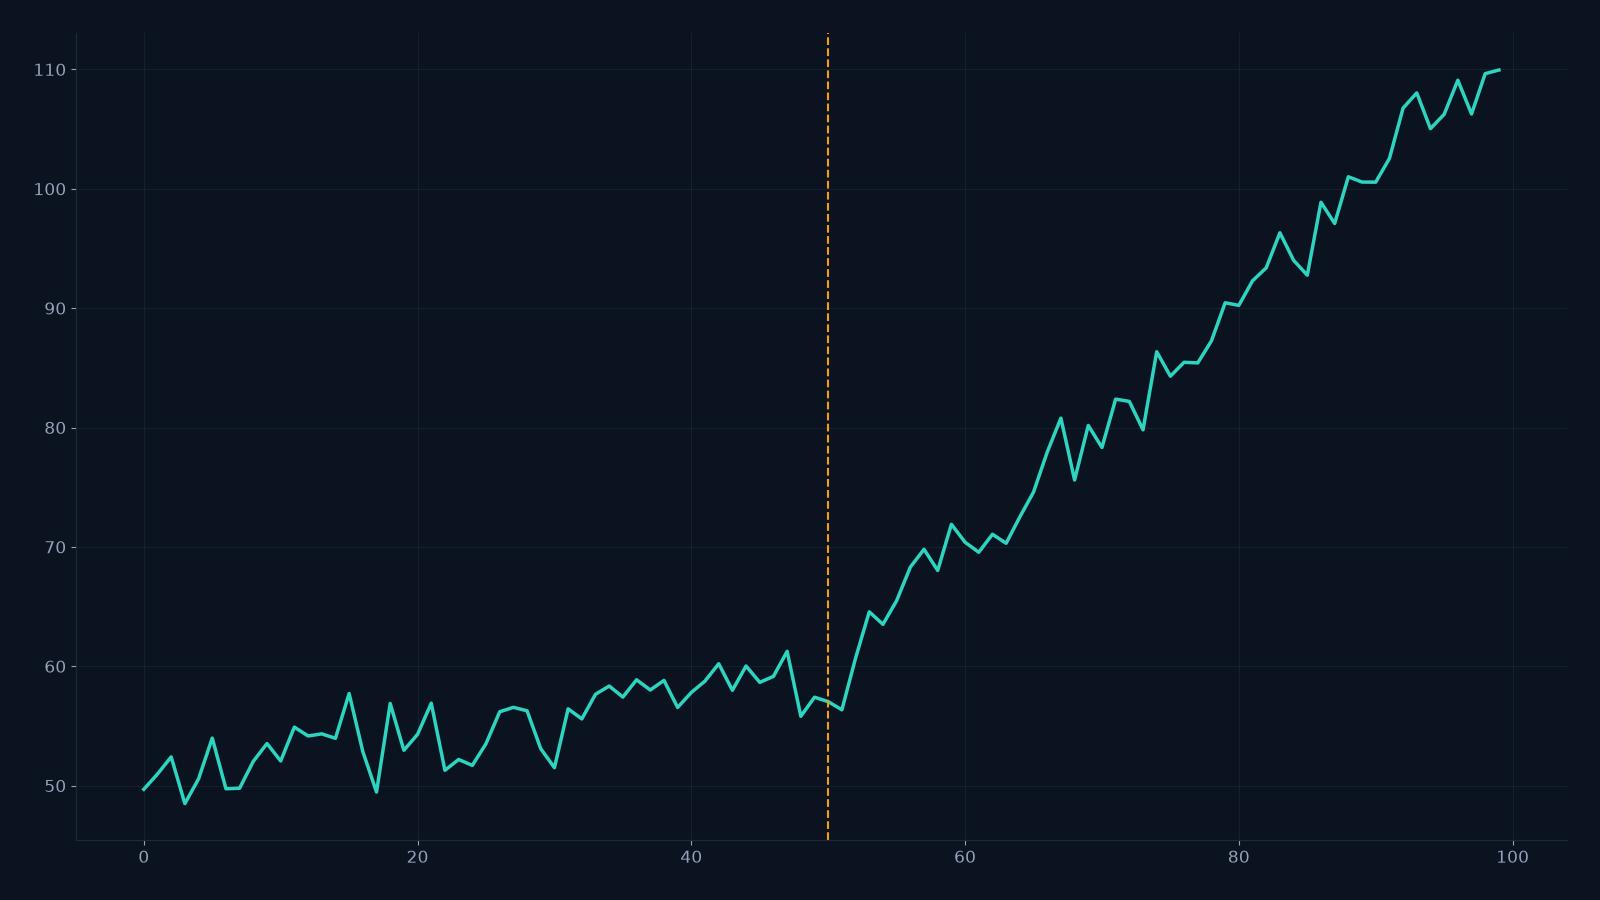
If the world changed in a way the history has never seen — a new competitor, a regulation, a pandemic — the model will extrapolate the old pattern. A zero-shot model has no causal knowledge. You need to encode the change as a covariate or override the forecast.
2. Promotions and interventions
A promotion is an intervention, not a pattern. If the history contains promotions, the model may learn an average effect, but it will not know the effect of a new promotion. Add a promotion flag as a covariate or model the lift separately.
3. Very short series
Most foundation models need enough history to infer a pattern. The studio requires at least 8 rows; a longer history usually produces a better forecast. If you have 3 points, use a human judgment or a simple rule, not a foundation model.
4. Series with no shared structure
Zero-shot transfer works when the new series resembles the training distribution. A highly specialized series with a unique data-generating process may need a custom model.
5. Causal questions
“What happens if I cut the price by 10%?” is a causal question. A forecasting model predicts the continuation of a pattern; it does not answer interventions.
How to set up a fair baseline
- Hold out the last 20–30% of the series.
- Forecast the holdout with the same horizon you will use in production.
- Score the median with MAE/RMSE or MASE.
- Score the interval with coverage: the actual should fall inside the 80% band about 80% of the time.
- Compare with seasonal naive and at least one classical model.
- Record latency and cost for the same batch.
If the zero-shot model does not beat seasonal naive, do not deploy it just because it is a foundation model. If it does, you have a baseline worth building on.
When to fine-tune
Fine-tuning makes sense when:
- You have a large, clean history for the target domain.
- The zero-shot model is close but consistently biased.
- You need to incorporate domain-specific covariates or constraints.
- The cost of a custom model is justified by the forecast value.
Mistral positions Timestral Forge for fine-tuning on proprietary data. Start zero-shot, measure the gap, then decide.
A practical workflow
- Paste or upload a series.
- Run a zero-shot forecast at the horizon you need.
- Check the median and the 80% band against the last known values.
- Backtest on a holdout.
- If the error is acceptable, deploy; if not, add covariates or fine-tune.
- Re-run the backtest when the data-generating process changes.
What to read next
- What is Timestral? — the model family.
- Timestral vs Chronos-2 — a testable comparison.
- How to evaluate forecasts — metrics and backtesting.
- API pricing — one credit per forecast call.
FAQ
Does zero-shot mean no data is needed?
No. You need a history for the series you want to forecast. Zero-shot means no training, not no input.
Can I fine-tune Timestral on my data?
Mistral positions Timestral Forge for fine-tuning. For many short-horizon problems, the zero-shot model is enough; measure the gap first.
Is zero-shot better than a classical model?
Not always. On short, stable series, seasonal naive or exponential smoothing can be hard to beat. Always include a classical baseline.